Health insurance is an important financial protection tool that helps individuals and families manage the cost of medical treatment. Hospitalisation, surgeries, diagnostic tests, and emergency medical care can create significant financial pressure, especially when unexpected health problems arise. However, many people purchase health insurance without fully understanding what their policy actually covers. Different plans offer different benefits, exclusions, waiting periods, and payment conditions. Understanding these details before purchasing a policy can help you avoid confusion when making a medical claim. Here is a practical guide to understanding health insurance coverage, benefits, exclusions, and hidden costs.
1. What Is Health Insurance?
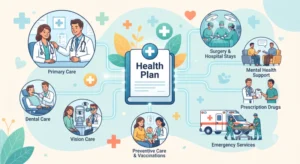
Health insurance is a financial agreement between an insurance company and a policyholder. In exchange for paying a premium, the insurer provides coverage for eligible medical expenses according to the policy terms.
Depending on the plan, coverage may include hospitalisation, medical procedures, diagnostic tests, medicines, and certain outpatient services.
The amount covered depends on the sum insured, policy conditions, deductibles, co-payments, and applicable exclusions.
2. Hospitalisation Expenses
Hospitalisation is one of the primary benefits offered by many health insurance policies.
Depending on the policy, covered expenses may include:
- Hospital room charges.
- Doctor and surgeon fees.
- Nursing services.
- Intensive Care Unit (ICU) expenses.
- Operation theatre charges.
- Prescribed medicines.
- Medical investigations.
However, insurers may apply room-rent limits, sub-limits, or other restrictions. It is important to understand these conditions before selecting a policy.
3. Pre-Hospitalisation and Post-Hospitalisation Coverage
Medical expenses do not always begin or end with hospital admission.
Many health insurance policies cover eligible medical expenses incurred before and after hospitalisation for a specified period.
Pre-hospitalisation expenses may include consultations, diagnostic tests, and prescribed medicines related to the condition requiring admission.
Post-hospitalisation benefits may cover follow-up consultations, medications, and additional investigations.
The covered duration and reimbursement conditions vary between policies.
4. Daycare Treatment Coverage
Some medical procedures require hospital facilities but do not require a full 24-hour hospital stay because of advancements in medical technology.
These treatments are known as daycare procedures.
Depending on the policy, examples may include certain cataract procedures, chemotherapy sessions, dialysis, and other eligible treatments.
Always check the policy’s daycare treatment list because coverage conditions may differ between insurers.
5. Ambulance Expenses
Many health insurance plans provide coverage for eligible ambulance expenses when a patient needs transportation to a hospital for emergency treatment.
However, coverage may have financial limits, documentation requirements, or specific medical conditions.
Some policies also offer air ambulance benefits under separate conditions.
6. Preventive Health Check-ups
Certain health insurance plans provide annual preventive health check-up benefits.
These check-ups may include selected blood tests, blood pressure measurements, cholesterol tests, and other diagnostic investigations.
The available tests and financial limits depend on the insurer and policy.
Preventive check-ups can encourage early detection of potential health concerns.
7. What Does Health Insurance Usually Not Cover?
Although health insurance offers several benefits, policies also contain exclusions.
Common exclusions or restricted benefits may include:
- Cosmetic procedures that are not medically necessary.
- Treatment for certain pre-existing conditions during applicable waiting periods.
- Non-medical or personal convenience expenses.
- Certain dental treatments.
- Routine outpatient consultations unless specifically covered.
- Experimental or unapproved treatments.
- Medical expenses related to excluded activities or conditions.
Exclusions vary by insurer, so reading the policy document is essential.
8. Understanding Hidden Costs in Health Insurance
A policy with a low premium may not always be the most affordable option in the long run.
Consider these possible expenses:
Co-payment: You may need to pay a percentage of eligible medical expenses yourself.
Deductible: You must pay a specified amount before the insurer begins paying covered expenses.
Room-rent limits: Certain policies restrict the amount payable for hospital accommodation.
Sub-limits: Specific treatments or medical services may have separate coverage limits.
Non-medical expenses: Items such as certain administrative or personal-use charges may not be covered.
Understanding these costs can help you estimate your actual financial responsibility during hospitalisation.
9. How to Choose the Right Health Insurance Policy
Before purchasing a health insurance plan, compare several important factors:
- Choose an appropriate sum insured based on your needs and location.
- Review the waiting period for pre-existing conditions and specific treatments.
- Check the hospital network and cashless treatment facilities.
- Understand co-payment and deductible conditions.
- Review exclusions and treatment-specific limits.
- Compare premium costs and renewal conditions.
- Check the claim procedure and required documentation.
Do not select a policy based on advertising claims alone. Read the complete policy wording.
10. Why Understanding Your Policy Matters
Knowing what your health insurance covers can help prevent unpleasant surprises during medical emergencies.
It allows you to understand which hospitals you can visit, what expenses may be reimbursed, and how much you may need to pay yourself.
You should also disclose relevant medical history accurately when purchasing a policy. Incorrect or incomplete information can create problems during claim assessment.